
Over more than 30 years of reform and attracting foreign direct investment, Vietnam has made significant strides in economic development. Foreign direct investment from multinational corporations (MNCs) offers a solution to the problem of improving economic management, attracting innovation and technological application, and creating jobs for workers. However, other shortcomings that need to be managed, such as tax evasion or even the complete failure to collect taxes from these MNCs, are always a concern for governments and are being addressed based on OECD recommendations.
Therefore, identifying transfer pricing practices and implementing effective transfer pricing control measures for multinational corporations is a top priority today, requiring collaborative efforts from countries around the world.
1. Transfer pricing that reduces profits or causes losses.
1.1. Transfer pricing through the purchase and sale of raw materials, semi-finished products, and goods with the parent company or affiliated companies.
This form of transfer pricing is carried out by multinational corporations headquartered in countries with high tax rates purchasing raw materials, semi-finished products, or finished products at high prices and then reselling them to other member companies at low prices to minimize profits, thereby minimizing tax payments, and even creating a situation of "fictitious losses, real profits," thus avoiding tax obligations. In many cases, the business does not directly transact with the parent company, but with its affiliated parties. In these cases, state management agencies, and in many instances even the joint venture participants, are unaware of the situation.
Similarly to the valuation of fixed assets mentioned above, businesses that are partners in special affiliated relationships also mutually agree on the price of raw materials supplied to each other, declaring a higher price than the market price.
This is also one of the ways companies transfer profits abroad by paying for imported goods to parent companies or branches within other multinational corporations. The import of raw materials from abroad by FDI enterprises is also one of the factors leading to recipient countries having a trade deficit.
1.2. Transfer pricing through the form of increasing the value of capital contributions.
This is one of the typical forms of transfer pricing when multinational companies make foreign investments in the form of joint ventures or establish wholly foreign-owned companies.
In joint venture investments, transfer pricing is implemented gradually in the initial stage through capital contributions: foreign investors contribute capital to the enterprise in the form of machinery, equipment, and technology. Most domestic enterprises, limited by financial resources, primarily contribute capital in the form of land use rights. However, the value of land use rights is often underestimated, while the machinery, equipment, and technology contributed by foreign investors are often specialized, outdated, or fully depreciated. Due to the limited capacity and expertise of domestic enterprises in valuation, and the lack of information and databases for comparison, these items are often valued significantly higher than their actual value during the valuation process.
For investments involving the establishment of 100% foreign-owned companies, increasing the value of contributed assets will help investors increase their annual depreciation rate, thus increasing input costs. This will help investors recover their fixed investment capital more quickly, thereby minimizing investment risks and reducing corporate income tax obligations in the host country.
1.3. Transfer pricing by artificially inflating the value of intangible assets and buying and selling fixed assets at inflated prices.
Another common form of capital contribution by foreign investors is the contribution of intangible assets: software, trademarks, formulas, etc. Determining the value of these assets is often difficult due to the lack of specific valuation standards. Foreign investors inflating the value of intangible assets during the capital contribution process increases their stake, thereby gaining more influence within the enterprise.
Besides contributing intangible assets, foreign investors also transfer production and business technology to affiliated parties in the investing country and collect royalties. According to current regulations in most countries, royalties are subject to a much lower tax rate than corporate income tax (most countries set tax rates for royalty income at 5%, 7,5%, 10%, or 15%). Thus, foreign investors save a considerable amount of net profit by switching from dividends to royalty payments.
In the case of the sale of tangible fixed assets, companies within multinational corporations headquartered in countries with high tax rates will purchase tangible fixed assets from companies headquartered in countries with low tax rates at prices significantly higher than the true value of those assets. Through this sale of fixed assets, a portion of the company's income is transferred abroad to another company within the same group. This reduces the company's profits, thereby decreasing the amount of tax payable.
Similar to the buying and selling of tangible fixed assets, companies will overvalue intangible fixed assets or pay for expenses related to branding, product development, advertising, and marketing at subsidiary companies located in countries with high corporate income tax rates. The costs incurred will be borne by the high-tax companies, while all subsidiary companies benefit equally. This minimizes tax payable and helps multinational corporations save on the costs of liquidating outdated fixed assets.
1.4. Transfer pricing by inflating administrative and management costs.
One of the positive effects of foreign direct investment on recipient countries, especially developing countries, is the opportunity to learn advanced management practices. However, an undeniable downside is that it is also a common practice for companies to transfer profits abroad under various guises.
- MNC subsidiaries hire managers at high salaries, and at the same time, they must pay a fee to the foreign parent company or other subsidiary for providing the managers.
- Businesses send specialists and workers to study and intern at the parent company at high costs. This is essentially a form of transfer pricing.
- Multinational corporations (MNCs) hire consultants from their parent companies and pay for their services, but it's difficult to determine the number and effectiveness of their services, making it hard to assess whether the costs incurred are high or low, appropriate or inappropriate. Although tax authorities notice irregularities, there is no basis to determine whether the company has inflated prices and expenses to take action against it.
Generally, the more businesses operate and the more experience they gain, the lower their overall costs become. However, management costs in these businesses tend to increase. As a cost closely related to internal business operations, based on internal regulations and contracts, this is also a cost that businesses can easily inflate, reducing profits or even causing losses, eroding the tax base, and evading tax obligations. The unusually high salaries of senior personnel from the parent company or from organizations with shared interests are also often a factor driving up input costs. It's worth noting that when FDI businesses engage in this form of transfer pricing, domestic joint venture partners are the most affected, as they cannot accurately determine the costs incurred compared to the benefits they receive.
1.5. Transfer pricing through inflated advertising costs
This is a form of transfer pricing used by many multinational corporations and FDI enterprises. This method is particularly common if the FDI enterprise exists as a joint venture where the foreign partner holds a controlling stake.
Inflating advertising costs, especially in countries lacking strict regulations on determining reasonable advertising expenses, advertising levels, and the ratio of advertising costs to total costs, can help FDI businesses achieve many objectives: creating the illusion of losses (very high revenue but even higher costs); and establishing a dominant brand image in the market.
1.6. Transfer pricing through direct lending
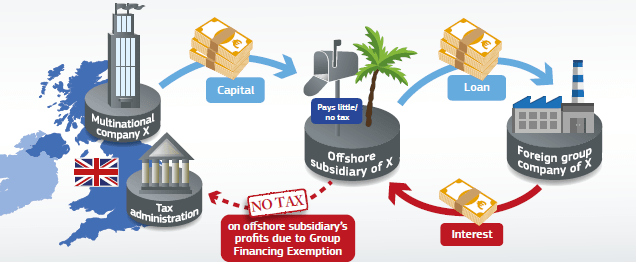
One of the common forms of transfer pricing today is through lending between members of an MNC. There are two common scenarios in which MNCs employ this form of transfer pricing:
- When a profitable business branch in a country with a high corporate income tax rate, that branch will lend to the parent company or other branches at low (or even zero) interest rates to help the entire MNC have capital to expand its market.
- When a subsidiary is located in a country with a high corporate income tax rate, it can borrow from the parent company or other subsidiaries at very high interest rates, thereby making its pre-tax profit (after deducting interest) negative and avoiding corporate income tax. Lenders are often headquartered in locations with low interest tax rates, thus maximizing the overall profit of MNCs.
2. Interest Transfer Pricing
This is a highly sophisticated form of transfer pricing employed by FDI companies – branches of multinational corporations (MNCs). Some common methods used by MNCs to carry out profit transfer pricing include:
FirstlyThe most noticeable example is that some FDI enterprises, after a short period of operation, apply to convert into joint-stock companies to list on the stock market. During this process, many enterprises have inaccurately valued their assets, exploiting the conversion to "capitalize assets," selling off shares, or even transferring all capital out of the host country, thereby generating profits for the parent company while disrupting the national capital flow.
MondaySome businesses, which are members of conglomerates, are applying for listing on the stock market; affiliated businesses have engaged in transfer pricing to increase the profits of the businesses that will be listed on the stock exchange. This will distort the financial statements of the issuing company, causing the share value to increase upon listing; creating price discrepancies for the issued shares, causing artificial imbalances in supply and demand on the stock market, and disrupting the market.
TuesdayIn the process of preparing for a business to gain a monopoly on the processing and distribution of certain goods or services in order to compete for market share in those goods or services, affiliated parties may transfer revenue and profits to that business. This practice also creates distortions in financial reporting and market assessments by investors, creates unfair competition among businesses, and suppresses small and medium-sized enterprises.
FinalIn a context where many countries are actively attracting foreign capital with the goal of rapid and sustainable growth, their governments have implemented numerous preferential policies for investors in various industries and sectors. Furthermore, when investing in different locations, affiliated businesses have transferred revenue and profits from other sectors, industries, and regions not eligible for incentives to the businesses already receiving incentives, thereby reducing tax payments and increasing the group's profits.
3. Risks for businesses when failing to declare transfer pricing.
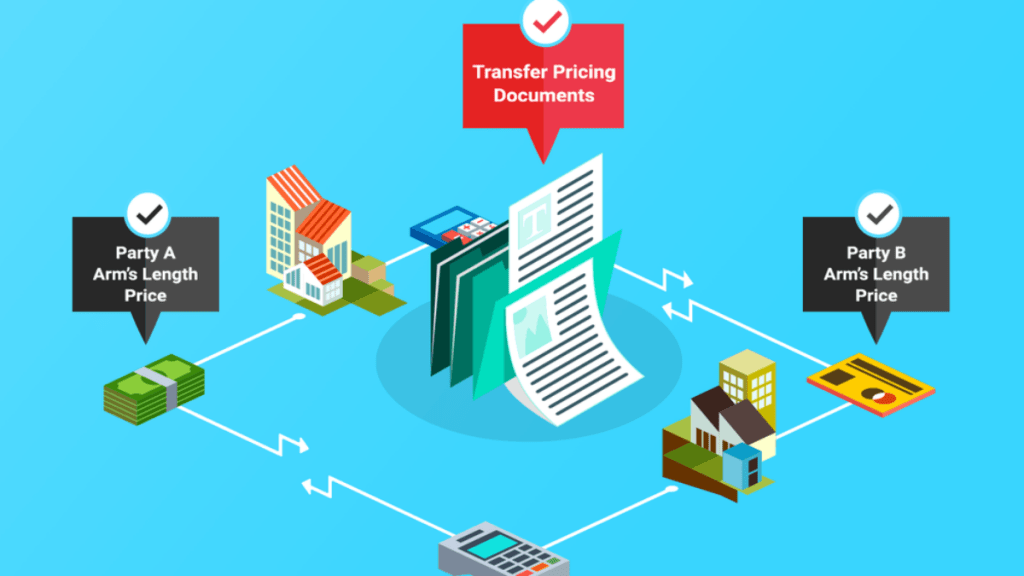
Transfer pricing involves two main risks: compliance risks related to transfer pricing documentation and declarations; and risks related to providing explanations during tax audits.
Regarding compliance risks related to transfer pricing records and declarations: these can be minimized through good compliance, proper filing, and complete disclosure as required by law.
Regarding the risk of having to explain the situation during a tax audit: this can be mitigated if businesses proactively research transfer pricing, its implementation methods, how to identify related parties and related-party transactions, determine prices, recognize deductible transfer pricing expenses, and understand the conditions for deduction.
Without a clear understanding, proper compliance, and the ability to explain the situation, businesses may face tax assessments, additional tax liabilities, back taxes, tax penalties, and late payment interest charges.
Furthermore, from the perspective of multinational corporations, the failure to declare transfer pricing results in a decline in the image and reputation of MNCs, and may even lead to investigations into transfer pricing by the governments of other countries where subsidiaries are located, as well as by the government of the head office.
4. When does the tax authority have the right to assess taxes?

- Taxpayers who fail to declare, declare incomplete information, or fail to submit Appendix 01 issued with the Decree on related-party transactions;
- The taxpayer provided incomplete information in the Transfer Pricing Documentation as stipulated in Appendices 01 and 03 issued with the Decree on related-party transactions;
- Failure to submit the Transfer Pricing Documentation and the data, documents, and materials used as the basis for comparative analysis and price determination in the Transfer Pricing Documentation as requested by the Tax Authority within the time limit stipulated in the Decree;
- Taxpayers use inaccurate or misleading information about independent transactions to analyze, compare, and declare transfer pricing.
- Based on documents and data regarding illegal or invalid certificates;
- Failure to specify the origin of the transaction in order to determine the price, profit margin, or profit allocation ratio applicable to the related-party transaction;
- The taxpayer has violated the regulations on transfer pricing as stipulated in the Decree on Related-Party Transactions.
See more:
- Learn about transfer pricing – Part 1: Tax Base and Profit Shifting
- Learn about transfer pricing – Part 3: Classification of related-party transactions and the principle that substance determines form
- Learn about transfer pricing – Part 4: Instructions on some aspects of the application form and documents.