
Recently, the General Department of Taxation noted several changes in the new guidelines of Circular 80/2021/TT-BTC regarding the 2021 tax settlement compared to the previous regulations. At the same time, the Department also encouraged taxpayers to submit their tax declarations through the tax declaration support application (https://thuedientu.gdt.gov.vn) for safety during the pandemic.
The cost of supporting Covid-19 prevention and control in Vietnam is deductible.
2021 was a difficult year due to the pandemic, therefore, to encourage timely contributions from businesses in the fight against the disease, the Government issued Decree No. 44/2021 guiding the implementation of deductible expenses when determining taxable revenue. Deductible expenses include donations and sponsorships. in money or in kind of the organization for its COVID-19 prevention and control activities in Vietnam.
Businesses must submit supporting documents for donations and sponsorships, including a confirmation record in the form issued with this Decree, bearing the signatures and seals of both parties; and legal invoices and documents in accordance with the law regarding donations and sponsorships.
Furthermore, according to Decree 92/2021 implementing Resolution No. 406/NQ-UBTVQH15 of the Standing Committee of the National Assembly on solutions to support the Covid-19 pandemic, the corporate income tax will be reduced by 30% if the enterprise's revenue in the 2021 tax period does not exceed VND 200 billion and is lower than the revenue in the 2019 tax period.
Note: For newly established, merged, split, or separated businesses during the tax periods of 2020 and 2021, the criterion of revenue in the 2021 tax period decreasing compared to the 2019 tax period does not apply.
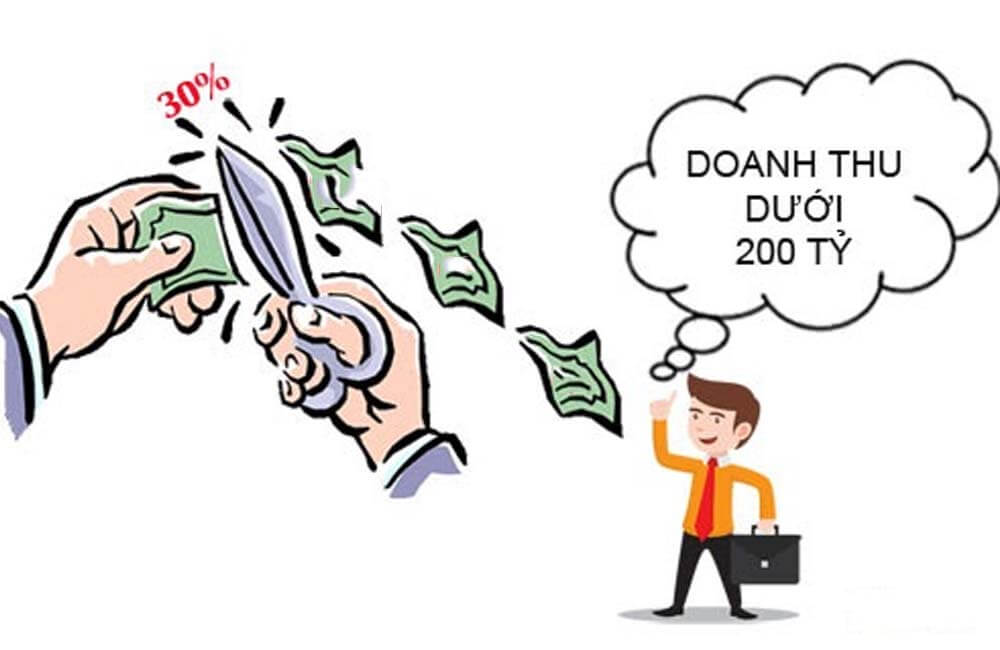
When preparing tax return documents, businesses declare corporate income tax reductions on the corporate income tax return and on the corporate income tax reduction appendix issued with Government Decree No. 92/2021/ND-CP dated October 27, 2021.
The deadline for submitting corporate income tax returns is the last day of the third month (March 3, 31.3.2022) from the end of the calendar year or fiscal year.
Other important notes
In addition to noting that expenses for supporting the fight against Covid-19 in Vietnam are deductible, individuals and businesses also need to pay attention to several points when filing their 2021 tax returns:
- There is no need to enter information into form 05/KK-TNCN; the software will automatically update the information in Appendices PL 05-1BK-TNCN, PL 05-2BK-TNCN, and PL 05-3BK-TNCN.
- If an individual has multiple sources of income, they must file their own tax return and cannot authorize someone else to do so.
- Businesses paying primary income calculate provisional tax according to the full progressive tax rate. Businesses paying other income calculate 10% from 2 million VND per payment and issue a withholding certificate so that employees can self-declare their tax.
- Businesses that make simultaneous payments only show personal income and the amount of tax withheld without marking the "Authorized Settlement" column on Form PL 05-1BK-TNCN.
- The total taxable income includes salaries and wages paid during the period to resident individuals with employment contracts of 3 months or more. This includes salaries and wages received for working in economic zones and income exempted or reduced under double taxation avoidance agreements.

- The total personal allowance includes the deduction for the taxpayer themselves and the deduction for dependents. Deduction for the taxpayer = 11 million VND/month, deduction for dependents = 4,4 million VND/month.
- If an individual's income is more than 2 million VND per payment, then when paying salaries, deduct 10% tax on the income before paying the employee and issue a tax deduction certificate. If the income is more than 2 million VND per payment and a commitment form (02/BCK-TNCN) is submitted, pledging that the income after deductions is below the tax threshold, then temporarily no personal income tax will be deducted, and the deducted amount will be adjusted and entered into the software.
- If no deductions are made, enter 0 to export and submit without errors. Item 19 is the total amount of personal income tax that the enterprise has deducted from resident individuals with employment contracts of 03 months or more during the period.
Regarding personal income tax, if an individual directly settles their tax return, the deadline for submitting the tax return is the last day of April 2022. If a business is authorized to settle its tax return, the deadline for submitting the return coincides with the corporate income tax settlement date, which is the last day of March 2022.