1. Building a centralized taxpayer database
1.1. Building a centralized taxpayer database
Information technology helps to accurately and efficiently aggregate and manage tax and invoice data, thereby creating clear insights into the financial situation of businesses.
- The tax authorities build a database of taxpayers, which is centrally managed at the General Department of Taxation.
- Implementing a centralized electronic invoice database and management system at the General Department of Taxation.
1.2. Developing data analysis tools based on information technology (AI)
By using technology to analyze data, the Tax Authority can generate early signs of potential tax and financial problems; the following are some of the tools used:
- The application supports full verification. The aim is to assess and select high-risk taxpayers. See the detailed article on Decision 970/QD-TCT on Tax Inspection Procedures (Effective from July 14, 2023) and The application supports full verification.
2. Data interoperability and data collection outside the tax authority.
The sources and methods for collecting information on tax obligations are as follows:
2.1. Gathering information within the tax authority
This includes information within the scope of collection and management by the tax authorities, namely: Tax registration information; personal information of founding members, owners, and legal representatives of taxpayers; information on related-party transactions…
2.2. Collecting taxpayer information from agencies other than the tax authority.
This information is collected from relevant government agencies, organizations, and individuals who are responsible for providing it, including:
3. Tax analysis, assessment, and audit based on tax risk rating.
3.1. Analysis and Evaluation
The tax authorities can identify businesses with higher risks and focus their audits on the most critical issues.
The tax authority's assessment and monitoring functions include:
- Collecting, processing, managing, and utilizing taxpayer-related information for risk management purposes.
- Assessing tax compliance and classifying taxpayer risk levels.
- Apply tax management measures corresponding to the levels of tax law compliance and the level of risk posed by taxpayers.
- Regulations on criteria and indicators for assessing compliance and classifying the risk level of taxpayers, both businesses and individuals.
The principles of management and control are as follows:
The tax authorities base their decision-making process on the results of the aforementioned tax compliance assessment and operational information available at the time of the decision to determine the list of taxpayers classified according to risk levels for each period.
The list of high-risk taxpayers under the above-mentioned cases is updated on the risk management application in tax administration.
a) High risk: Review, check, verify; Inspection, audit
b) Medium risk: Randomly select individuals to be included in the review, inspection, and verification list; continue performing risk classification for the next assessment period.
c) Low risk: Maintain records and perform risk level classification for the next assessment period.
For cases of high compliance: Include in the list for consideration and selection for commendation and reward of taxpayers who comply with tax laws.
See detailed instructions: Tax risk assessment and targeted taxpayer monitoring effective from July 2, 2021.
3.2. Tax audits based on risk ratings
In order to conduct quick checks on high-risk taxpayers, the tax authorities apply "The application supports full verification." with the following procedure:
Step 1: Check your tax records: No later than 25 days after the tax filing deadline, tax officials assigned to conduct tax audits will use audit software to inspect and compile a list of high-risk taxpayers.
Step 2: Process the test results and provide notification: For tax returns assessed as having a high overall risk score, a list will be created on the application for on-site inspection at the tax authority's headquarters. Simultaneously, the results from this inspection will be integrated into the tax authority's audit plan and on-site inspection plan.
Thus, this process helps tax authorities focus on quickly auditing taxpayers at high risk of tax compliance through the use of a comprehensive audit support application. This enhances the ability to manage and handle cases with a high risk of tax violations.
4. Closely monitor sales transactions through an electronic invoicing system.
4.1. Electronic invoice analysis and management system:
The General Department of Taxation is implementing a system to analyze and manage electronic invoices from taxpayers.
This system will be able to compare electronic invoice data with tax returns, assess invoice usage, identify suspicious areas, and issue risk warnings.
See the detailed article. Implementing a database analysis and electronic invoice management system.
4.2. Applying the K coefficient to check for invoices exceeding safe limits.
On June 14, 2023, the General Department of Taxation issued... Official document No. 2392_TCT_QLRR dated June 14, 2023, regarding the inspection of electronic invoices.Accordingly, proactively check taxpayers who issue invoices exceeding safe limits.
In it, the General Department of Taxation stated that it has developed functions on the electronic invoice application to meet the requirements for controlling electronic invoices and preventing the issuance of fraudulent invoices. Some of the main functions are as follows:
– The system automatically controls the total value of goods sold on issued invoices against a threshold of input value calculated as K times the total inventory value and the total value of goods purchased.
– The warning system operates according to parameter K.
How to calculate the coefficient K
According to Official Letter 2392/TCT-QLRR of 2023, the coefficient K is used to control the total value of goods sold on issued invoices against the threshold value of input goods, calculated using the following formula:
K = Total value of goods sold on the invoice / (Total value of inventory + Total value of goods purchased on the invoice)
Accordingly, when a business exceeds the threshold for input goods value, calculated as K times the total value of inventory and the total value of purchased goods, the system will issue an invoice alert and add the business to the management list.
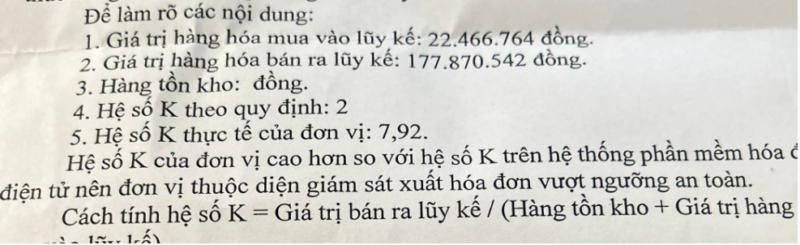
Some examples of requests for explanation due to exceeding the threshold according to the K factor.
Below are some requests for explanation due to exceeding the K coefficient threshold.

Shortcomings of the K coefficient:
Because the K coefficient is calculated using mathematical logic without considering other conditional factors, the mechanical application of this coefficient may trigger audit warnings but in reality, there is no risk. For example, some types of processing businesses with revenue many times higher than the value of inventory + inputs fall into the risk category even under normal business conditions.
5. What should businesses do to avoid tax risks?
We can draw one key conclusion: Businesses need to manage their finances, accounting, and tax filing processes rigorously and in compliance with the law. The goal is to ensure that your business is on the list of top-performing businesses. businesses that "perform well" instead of having to face being inside list of “violations”.
To achieve this, here are some important tips for both businesses and individuals:
- Understand the legal regulations: Familiarize yourself with the regulations and guidelines related to data provision, tax filing, and tax payment. Ensure you understand the procedures and any legal limitations and obligations you need to comply with.
- Data systematization: Establish and maintain a reliable financial, transaction, and tax management system. This will allow you to easily access the necessary information when requested by the tax authorities.
- Monitor closely: Ensure that you have accurately recorded all financial information. Check regularly to ensure the accuracy of the data.
- Get ready for inspections and audits: Ensure that you have the necessary data and information ready to face any audits or inspections from the tax authorities.
- Keep relevant documents: Keep all tax and financial documents and records on file for the required period. This will help you demonstrate the accuracy and compliance of your information when needed.
- Collaborate with financial and tax experts: Collaborate with experienced financial and tax professionals or consulting firms to ensure you follow the correct procedures and comply with legal regulations.
Remember, complying with regulations and following proper procedures not only helps you avoid legal risks but also contributes to the transparency and financial health of your business.
Implementing the above is not easy for businesses; the effective solution is to use professional services: Collaborate with financial, accounting, and tax experts to ensure you follow the correct procedures and comply with legal regulations.
See detailed information about our services in the article.
Accounting and tax consulting services.