Recently, Deputy Prime Minister Le Minh Khai issued... Decree 12/2023/ND-CP effective from date 14.04.2023 until the end of the day 31.12.2023 Regarding the extension of the deadline for paying taxes and land rent for 2023, including value-added tax (VAT), corporate income tax (CIT), and personal income tax (PIT).
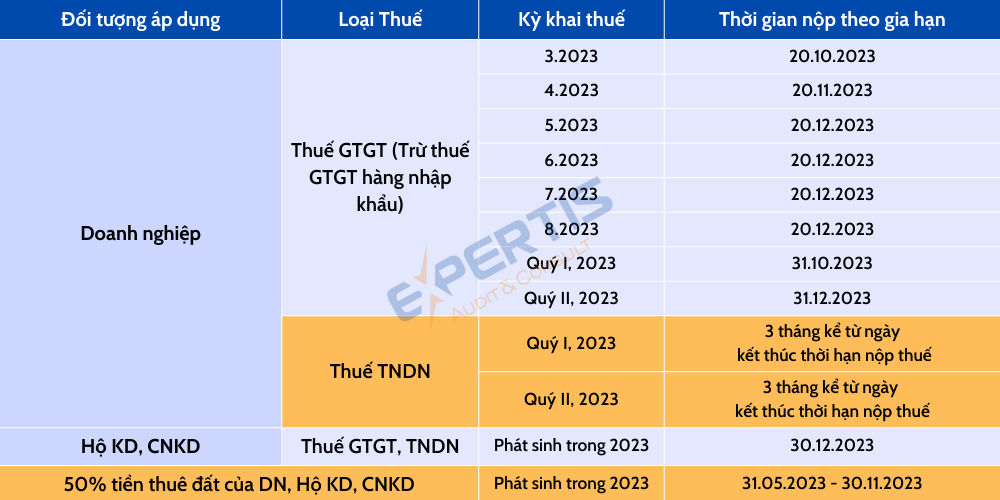
Details regarding the extension of the deadline for paying taxes and land rent in 2023.
1. Extension of the deadline for paying VAT (excluding import VAT)
The regulations regarding the extension of the deadline for paying Value Added Tax (VAT) (excluding import VAT) due (including tax allocated to other provincial localities where the taxpayer has its head office, and the tax payable on a per-transaction basis) for the tax period from March to August 2023 (for monthly declarations) and the first and second quarters of 2023 (for quarterly declarations) are as follows:
VAT tax from March to May 2023 and the first quarter of 2023 has an extension period of 6 months;
- The VAT payment deadline for June 2023 and the second quarter of 2023 is extended for 5 months.
- The VAT payment deadline for July 2023 is extended for 4 months.
- The VAT payment deadline for August 2023 is extended for 3 months.
Businesses and organizations are granted an extension to file monthly and quarterly VAT returns according to current regulations, but are NOT yet required to pay the VAT payable arising from the filed VAT returns.
The extension period begins from the date of the VAT payment deadline as stipulated by law. Specifically, the VAT payment deadline during the extension period is as follows:
- The deadline for tax payment for the April 2023 tax period has been extended to November 20, 2023 at the latest.
- The deadline for tax payment for the April 2023 tax period has been extended to November 20, 2023 at the latest.
- The deadline for tax payments for the tax periods of May, June, July, and August 2023 has been extended to December 5,6,7,8, 20.12.2023 at the latest.
- The deadline for tax payment for the first quarter of 2023 has been extended to October 31, 2023 at the latest.
- The deadline for tax payments for the second quarter of 2023 has been extended to December 31, 2023 at the latest.
In cases where branches or subsidiaries file separate value-added tax returns with the tax authority directly managing them, these branches or subsidiaries are also eligible for the extension of value-added tax payment deadlines.
If a branch or subsidiary of an enterprise or organization granted a tax extension does not engage in production or business activities within the economic sector or field for which the extension was granted, then that branch or subsidiary is not eligible for a value-added tax payment extension.
2. Extension period for provisional corporate income tax payments for the first and second quarters of 2023.
The extension period is 3 months from the date of the deadline for filing corporate income tax returns as stipulated by law.
Branches and subsidiaries of enterprises and organizations are eligible for an extension of corporate income tax payment if they file separate corporate income tax returns with the tax authority directly managing the branch or subsidiary.
Branches and subsidiaries of enterprises and organizations that do not engage in production or business activities within the economic sectors or fields eligible for the extension are not eligible for the extension of corporate income tax payment.
3. Extension of deadline for paying VAT and personal income tax for household businesses and individual business owners.
The deadline for tax payment will be extended to December 30, 2023, for household businesses and individual business owners operating in the economic sectors and fields specified in this Decree.
4. Land lease payment extension
The extension period is 6 months (from May 31, 2023 to November 30, 2023) for 50 % The amount of land lease fees payable in 2023 by enterprises, organizations, households, business households, and individuals who are subject to the regulations and are directly leasing land from the State.
Eligible entities for tax and land rent payment extensions

According to this Decree, The entities eligible for extensions of VAT, personal income tax, corporate income tax, and land rent include four groups of subjects.
1. Businesses, organizations, households, business households, and individuals engaged in production activities in the following economic sectors:
- Agriculture, forestry, and fisheries;
- Manufacturing industries: clothing, leather and related products; products from straw, woven materials; paper and paper products; rubber and plastic products; other non-metallic mineral products; metals; manufacturing of electronic products, computers and optical products; automobiles and other motor vehicles; beds, cabinets, tables, and chairs; mechanical processing; metal treatment and coating; food production and processing; textiles; wood processing and manufacturing of wood, bamboo, and rattan products (excluding beds, cabinets, tables, and chairs).
- Build;
- Publishing activities; film, television production, sound recording and music publishing;
- Exploiting crude oil and natural gas
- Manufacture of beverages; printing and reproduction of all kinds; manufacture of coke and refined petroleum products; manufacture of chemicals and chemical products; manufacture of prefabricated metal products (excluding machinery and equipment); manufacture of motorcycles and scooters; repair, maintenance and installation of machinery and equipment;
- Drainage and wastewater treatment.
2. Businesses, organizations, households, business households, and individuals engaged in business activities in the following economic sectors:
- Transportation and warehousing; accommodation and food services; education and training; healthcare and social assistance; real estate;
- Labor and employment services; travel agencies, tour operators and related support services;
- Creative arts, arts and entertainment; libraries, archives, museums and other cultural activities; sports, recreation; film screenings;
- Broadcasting and television; programming, consulting and other computer-related activities; information services;
- Mining support services.
3. Enterprises, organizations, households, business households, and individuals engaged in the production of priority-development supporting industrial products and key mechanical products.
4. Small and micro enterprises are defined according to the provisions of the Law on Support for Small and Medium-Sized Enterprises of 2017.
Taxpayers eligible for an extension of the deadline for paying taxes and land rent should submit their applications. Request for Extension to the tax authority in charge before the deadline 30 month 9 year 2023 to be granted an extension as per regulations.