Line Vertical Thin Streamline Icon: https://streamlinehq.com

Tax services

Related party transaction advisory services

We help you fully comply with tax regulations regarding related-party transactions and provide explanations to tax authorities during tax audits of related-party transactions.

Related party transactions

Bringing you peace of mind.

Ensure compliance with the law.

We help you ensure compliance with the law and avoid legal risks with the constantly changing tax regulations.

Save time and effort.

We have a team of experienced professionals with extensive tax knowledge to help you save time and effort.

Positive local relations

Obstacles and difficulties in the tax refund process are resolved through active consultation with local authorities.

Related party transaction advisory services

What affiliate marketing advisory services offer.

The specific scope is tailored and guaranteed to deliver effective results for each business.

Consulting on identifying relationships

We will advise on whether a business has related-party transactions that fall within the scope of the law on related-party transactions, or do not.

Create a related party transaction record.

We advise and assist businesses in preparing related-party transaction documentation, including: Country documents; Global corporate information documents; and Country-by-Country earnings reports.

Prepare a related party transaction declaration.

Providing advice on related-party transaction declarations for cases as required by regulations.

Explanation of transfer pricing audit

  • Consulting services for working with tax authorities.
  • Review and analyze transfer pricing risks and opportunities.
  • Protecting records from transfer pricing audits.

Price list for services to prepare Related Party Transaction Documents.

The right solution for your specific situation.

The cost of preparing related-party transaction documentation depends on the size of the business, the number of related-party transactions, the complexity of the documentation, and the requirements for international comparative data.

Standard Package

Businesses have simple transactions.

For businesses subject to the requirements of preparing Annexes I, II, III and the National File (Local File), the estimated service fee for preparing related-party transaction documentation is approximately VND 40.000.000 – VND 90.000.000.

Advanced package

FDI enterprises possess intangible assets.

For businesses that are required to create a Local File, Master File, and use international data, the estimated service fee for preparing related-party transaction documents is VND 85.000.000 – VND 185.000.000.

Special package

large multinational corporation

The complete set of 3 levels of transfer pricing documentation, including the Country-by-County Profit and Loss Report (if required), has an estimated service fee of VND 220.000.000 – VND 380.000.000.

Explanation Package

Review and support for audit explanations

In cases where a business is under audit and requires a review of data, assistance in explaining and defending its records, the service fee will be agreed upon based on specific costs appropriate to the business's circumstances.

Related party transaction advisory

Not sure which package is right for you?

Schedule a free 30-minute consultation — our experts will help you choose the best solution.

Related party transaction advisory services

Why choose Expertis?

Reputation
Dedicated
Security
For the customer
01
23+ years of practical experience
Established in 2003 — with experience in thousands of cases, we have a deep understanding of the history of accounting and taxation and how it has changed over the years.
02
Dominance
International standards combined with local expertise and professional management processes.
03
Strong team of professionals
Auditors, lawyers, tax consultants, payroll specialists — each issue has the right person to handle it.
Expertis full-service accounting services

Related party transactions

Businesses often ask

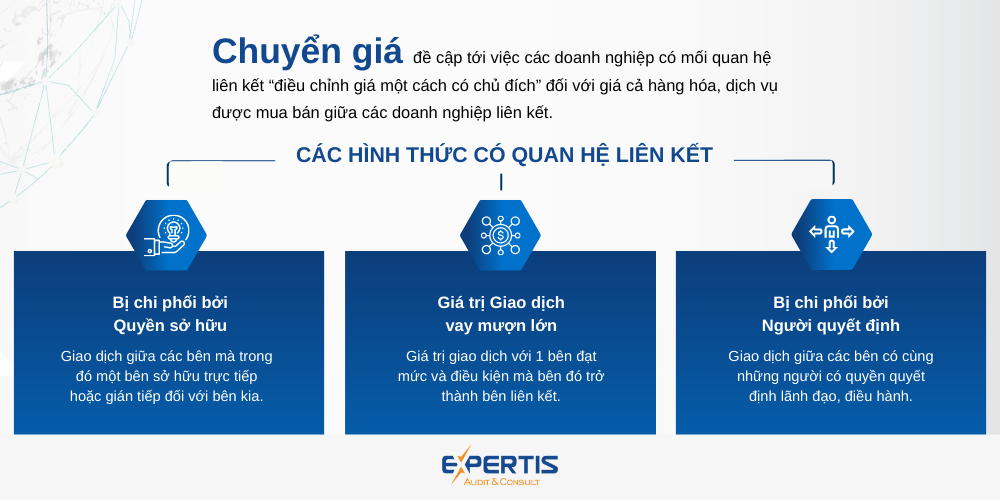
The definition of related parties is quite broad and detailed as follows:

1. Related parties (hereinafter referred to as "related parties") are parties that have a relationship falling under one of the following categories:

  • One party is directly or indirectly involved in the management, control, capital contribution, or investment in the other party;
  • The parties are directly or indirectly subject to the management, control, capital contribution, or investment of another party.

2. The affiliated parties referred to in Clause 1 of this Article are specifically defined as follows:

a) One business directly or indirectly holds at least 25% of the owner's equity of the other business;

b) Both businesses have at least 25% of their owner's equity held directly or indirectly by a third party;

c) One enterprise is the largest shareholder in terms of owner's equity and directly or indirectly holds at least 10% of the total shares of the other enterprise;

d) An enterprise guarantees or lends capital to another enterprise in any form (including third-party loans secured by related-party financing and similar financial transactions) provided that the loan amount is at least 25% of the owner's equity of the borrowing enterprise and accounts for more than 50% of the total value of the borrowing enterprise's medium and long-term debts;

e) An enterprise designates a member of the executive board or controlling entity of another enterprise, provided that the number of members designated by the first enterprise accounts for more than 50% of the total number of members of the executive board or controlling entity of the second enterprise; or a member designated by the first enterprise has the authority to decide on the financial or operational policies of the second enterprise;

f) Two businesses have more than 50% of their board members or have a board member with the authority to decide on financial or business policies designated by a third party;

g) Two businesses are managed or controlled in terms of personnel, finance, and business operations by individuals who are related to one of the following: spouse; biological parents, adoptive parents, stepfather, stepmother, parents-in-law; biological children, adopted children, stepchildren of the spouse, daughter-in-law, son-in-law; siblings with the same parents, half-siblings, half-siblings; brother-in-law, sister-in-law, daughter-in-law, son-in-law of a person with the same parents or half-siblings; paternal grandparents; grandchildren; aunts, uncles, and nieces/nephews.

h) Two business establishments have a head office and permanent establishment relationship, or both are permanent establishments of a foreign organization or individual;

i) Businesses that are controlled by an individual through that individual's capital contribution to the business or direct participation in its management;

j) Other cases in which one enterprise is subject to the actual management, control, and decision-making power over the production and business activities of the other enterprise;

k) The enterprise has transactions involving the transfer or acquisition of at least 25% of the owner's capital contribution during the tax period; borrowing or lending at least 10% of the owner's capital contribution at the time of the transaction during the tax period with individuals managing or controlling the enterprise or with individuals in a relationship as stipulated in point g of this clause.

In case you have related-party transactions but fail to submit related-party transaction reports as required:

The tax authorities have the right to determine the price; profit margin; profit allocation ratio; taxable income or the amount of corporate income tax payable for taxpayers who do not comply with regulations on declaring and determining related-party transactions; or who do not provide or provide incomplete information and data for declaring and determining the price of related-party transactions.

"Tax Authority Database" refers to information and data collected, compiled, and managed by the Tax Authority from various sources as stipulated in the Law on Tax Administration, including databases and information exchanged with tax authorities and competent authorities abroad.

regulations on related-party transactions

Zalo
FREE CONSULTATION
Related party transaction advisory services
We will advise you on your issues and propose solutions that are thorough and best suited to your tax needs and goals.
CONTACT US DIRECTLY